Originally published December 16, 2019 | Updated August 2026
Some health professionals have been able to incorporate their practice for over two decades, since 2001, and the list of professions permitted to incorporate has continued to grow year after year. This opened the door for health professionals to enjoy similar benefits that other regular incorporated businesses have been able to use for years. However, there are important restrictions unique to health professional corporations that are not found in other corporation set-ups, such as restrictions on who can be shareholders of the health corporation and types of acceptable income generated within a health professional corporation, to name a few.Incorporation also has to make sense financially. Just because you can incorporate does not mean you should. This article is written with the goal of helping health professionals understand the important advantages, disadvantages, restrictions and planning opportunities involved with incorporating a health practice.
Physicians and Surgeons
Psychologists
Dentists
Denturists
Pharmacists
Physiotherapists
Chiropractors
Audiologists
Massage Therapists
Chiropodists
Dieticians
Speech-Language Pathologists
Opticians
Occupational Therapists
Respiratory Therapists
Veterinarians
Midwives
Optometrists
Nurses
The main benefit of incorporation for a health professional is the tax deferral that arises from the difference between the corporate tax rate and the personal tax rate. Currently, active business income earned in a corporation, such as rendering health professional related services, is subject to a combined corporate tax rate of 11.2% in Ontario on its first $500,000 of income starting July 1st, 2026, and 26.5% for each dollar after. In contrast, the highest personal tax rate for individuals in Ontario is 53.53%, or 53.31% in Quebec. Incorporation, in most cases, for a health professional should only be considered when that professional generates more money than they need to subsidize their family personal living expenses and RRSP contributions when applicable or desired. If every single dollar generated is needed for yearly expenses, then incorporation might not be the appropriate option.
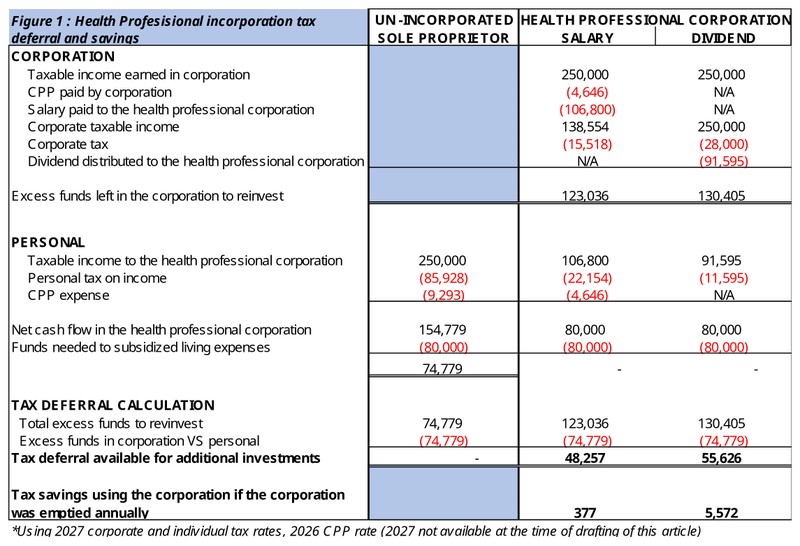
Consider a health professional who makes $250,000 a year but only requires $80,000 after taxes to subsidize their living expenses. After paying personal taxes, this individual would be left with only $74,779 to reinvest. If this same health professional was instead incorporated, after removing $80,000 net of tax required for living expenses in the form of either salary or dividends, they would have either $123,036 or $130,405 remaining in the corporation to reinvest as they choose. In this case, incorporating the practice leads to an additional $48,257 to $55,626 in excess funds to reinvest in the corporation, leading to growth of the business, reserve funds, or additional retirement funding. In the same example, if instead the individual required every dollar to subsidize their living expenses, there would be no deferral, and the savings would only be either $377 or $5,572.
Shares of a health professional corporation may qualify for the lifetime capital gains exemption currently sitting at $1,275,000 for 2026. Therefore, if a health practitioner plans to be able to sell the shares of their health professional corporation, or any qualifying corporation, the first $1,275,000 of the sale price will be tax free. Depending on their personal marginal tax rates, this could represent a saving of up to $341,000 from taxes in Ontario. There are a few criteria that must be met in order to qualify for the capital gains exemption, such as limiting total passive investments in the professional corporation and the ownership period. If selling the shares is a possibility for someone’s practice, then careful planning is necessary to ensure that the exemption is available at the time of the sale. Under certain conditions, an unincorporated health professional could even incorporate prior to selling their practice in order to take advantage of the capital gains exemption.
One of the most important restrictions for health professional corporations is regarding the ownership of the corporation. For most health professions, only registered professionals are allowed to be shareholders of a health professional corporation. For example, in a physiotherapist’s professional corporation, only individuals registered with the College of Physiotherapists are allowed to be shareholders. Therefore, a spouse who is not a physiotherapist cannot be a shareholder. Holding corporations and family trusts are also prohibited from being shareholders of most health professional corporations in Ontario.
Fortunately, some governing bodies do allow for additional carve-outs. For example, for doctors and dentists the legislation was amended to allow family members to hold non-voting and non-participating shares, as well as trusts for the benefit of minor beneficiaries. These exceptions currently do not apply to other health professional corporations in Ontario.
There are situations where some health professions’ governing bodies will accept health professionals operating under clinics or management corporations instead of being a professional corporation. For example, it is very common for physiotherapists to organize their practice as an incorporated clinic instead of a professional corporation. This is because the College of Physiotherapists of Ontario usually accepts a structure where a clinic hires a physiotherapist to provide treatment for the clinic’s patients, instead of the clinic being a professional corporation itself. This then allows the clinic to be considered a regular corporation without the restriction of only having a physiotherapist as shareholder, allowing any individual to be a shareholder and avoiding other restrictions unique to professional corporations. Unfortunately, not all governing bodies accept this structure. For example, those for doctors, dentists and chiropractors would not accept these types of arrangements.
Another exception to the general rule is that a pharmacist in Ontario is allowed to operate a pharmacy in a regular corporation as long as 51% of all voting and participating shares are held by a pharmacist. In order to fall within some of the exceptions of being able to operate your business under a regular corporation, the governing body must have a policy to accept those types of structure. If not, you must operate under a health professional corporation and abide by the regular restrictions that come with having one.
A health professional corporation may not carry on a business other than the practice of the profession, unless it is ancillary to the practice of the profession, or otherwise accepted by their respective governing body. Health professional corporations may reinvest their surplus funds, for example in mutual funds, GICs or on the TSX, but they should not get loans in order to fund the purchase of investments. The purchase of real estate to use for your own practice should be considered an acceptable ancillary activity, but the purchase of real estate for the purpose of earning passive rental income would not. Keep in mind that at retirement, the health professional corporation will need to be amended to no longer be a professional corporation, and therefore the corporation will no longer have these investment restrictions.
In a regular corporation, liability is usually limited to the assets in the corporation and not to the shareholders. For a health professional corporation, the shareholders have the added benefit of protection against civil liability, but not for professional negligence. If liability is of real concern, it would be prudent to properly consult with your governing body and discuss with your lawyer and accountant to find out if there are other corporate structures that are allowed for your profession that are more suitable.
Incorporation can offer significant tax and planning opportunities, but the right structure depends on your profession, income, governing body and long-term goals.
Initial Set-Up Costs
Potential legal costs, registration with the appropriate governing body and other incorporation expenses.
Ongoing Professional Corporation Costs
Cost of maintaining your health professional corporation with the governing body, including potential audits and other requirements.
Annual Accounting Costs
Annual accounting fees for preparation of the corporate tax return, bookkeeping and financial statements.
Audit Risk
Risk of potential CRA audits.
All of these factors should be considered when deciding if incorporation is the right choice for your practice.
As shown in Figure 1, where the health professional earns a net of $250,000 but only requires $80,000 to subsidize their living expenses, that same individual can decide to pay themselves either in the form of a salary or a dividend, or a mix of both. Figure 1 demonstrated that going 100% dividend meant the corporation would retain $7,369 more a year compared to going 100% salary. But that is usually only the first step in deciding whether salary or dividend is the better option for the health professional. Other factors must be considered, such as the value of the Canada Pension Plan contribution. Under salary, a total of $9,293 is contributed, while none is contributed for the dividend. The creation of RRSP room must also be considered. Only salary creates RRSP room, not dividends. Various other personal credits might also require salary income. For example, the child care tax credit requires salary, not dividend, to claim. The answer is never as simple as the result of the math, but this is a flexibility that is afforded only to those who are incorporated. Those individuals can also control how much funds they want to remove year to year from the corporation in order to defer taxes to another fiscal year. It is important to discuss the option of salary and dividend, or a mix of both, with your accountant in order to put forth a good game plan.
Income splitting is not easily achieved with professional corporations for various reasons. At the top of that list is the limitation on who can be a shareholder. Health professional corporations, apart from doctors and dentists, can only have professionals as shareholders, therefore limiting the possibility of income splitting with dividends. Further to possible restrictions imposed by the health professional’s governing body, restrictions imposed by the Income Tax Act must also be considered. TOSI, short for “tax on split income,” might restrict the possibility of income splitting, and general provisions such as “reasonableness” might also restrict the use of salary for spouses and children.
Without going over all possibilities, there are still some ways to achieve different levels of income splitting with family members. For starters, reasonable salaries could be given to family members as long as the salary is “reasonable” and in line with the work performed. In the case of health professional corporations that are allowed to have family members as shareholders, there are two main possibilities to successfully income split by giving shares to family members:
20 Hours Per Week
If the family member works 20 hours a week for the health professional corporation, then they might be entitled to dividends.
Age 65
Once the professional reaches the age of 65, they are able to distribute dividends to their spouse without further restrictions.
Other arrangements can also be made to create management corporations, which could in turn charge an administration fee to the health professional corporation for managing everything non-health related. This management corporation would not be restricted to the health professional corporation rules since it is not a professional corporation and would not offer health-related services. However, the application of TOSI and other tax rules would still apply.
Holding corporations could also be contemplated where the health professional corporation could make loans to the holding in order for the holding corporation to make investments that the health professional corporation would not be allowed to do. A holding corporation would also have no restrictions on who may be a shareholder, but again the potential application of TOSI affecting these types of structures must not be forgotten.
For health professionals whose governing bodies have accepted that they can practise through clinic-type corporations, those structures would have an easier time income splitting, since there would be no restrictions on who can be a shareholder or how to invest the funds. Those types of corporations might also be able to multiply the capital gains exemption with family members at the time of the sale.
Conventional retirement planning for health professionals would have consisted of maximizing RRSP and TFSA, which have a limit of $33,810 and $7,000 in 2026 respectively, and then investing the rest in unregistered investments that are fully taxable. When you are incorporated, you have the flexibility to start investing by using the corporation as an investment vehicle instead of having personal unregistered investments. Keep in mind, in our earlier example, our health professional who only needed $80,000 for their living expenses had an excess of between $123,036 and $130,405 in the corporation to reinvest, while they would have only $74,779 if they weren’t incorporated. This gives them an additional $48,257 to $55,626 yearly to reinvest in what could be a retirement fund, which should grow over time and be withdrawn later in retirement. Having a corporation means having the option and flexibility of having investments in RRSP, TFSA, and in a corporation as an investment vehicle. Appropriate planning is required to decide on the proper mix of RRSP, TFSA and corporate investments. For some, a corporate investment is a better option than RRSP and TFSA. Others will want to contribute the maximum to RRSP and TFSA while leaving the excess in the corporation to reinvest and grow. Every situation is different and unique and needs to be properly analyzed. There are also specific types of investments that should be prioritized inside a corporation rather than in RRSP and TFSA and vice versa.
Owning life insurance is an important part of any proper family and estate planning. As an incorporated business, you will have the option of having the corporation own the life insurance policy and the corporation can be the beneficiary of the policy, compared to owning the policy personally and having family members as beneficiaries. Life insurance payments, in most cases, are not deductible in the corporation, in the same way as they are not deductible on a personal tax return. However, since the corporation is taxed at a lower tax bracket, it is often much cheaper to own the policy through the corporation. For example, let us compare a policy that costs $10,000 per year for a health professional at a marginal tax bracket of 40% or at their corporate tax rate of 11.2%. That individual will require $16,667 of personal income to pay the personal life insurance of $10,000, but the corporation requires only $11,261 to pay for that same policy. Therefore, there would be a yearly saving of $5,406 in cash flow to finance the same policy.
Owning life insurance through a health professional corporation could be an interesting option, but it is not for everyone. For example, if this is a practice where we plan to sell in a few years, we might not want to put the life insurance policy in the same corporation that will be sold. It could be very costly for the professional to remove that policy before an eventual sale, therefore careful planning is required.
HEALTH PROFESSIONAL INCORPORATION
If you are considering incorporating your health profession, we can help you evaluate the tax, planning and structural considerations involved. You should also confirm the specific incorporation requirements with your governing body.
Contact Robert CPA →